Your Paycheck (W-4)
Fixable any week of the yearHanding HR an updated W-4 stops the interest-free loan to the IRS and puts your own cash back into your next paycheck.
 For my 35th birthday, I picked 35 winners from thousands on my email list. You're one of them. – Preston
Answer a short questionnaire about your money and goals. Within 7 days, you get every move that fits you, in order, each with a dollar figure and a deadline.
$1,500 for a $5,600 total value
Or 12 interest-free payments of $125 with Splitit.
My $10,000 promise: If your plan projects less than $10,000 in first-year value, one email gets you a full refund, and you keep the plan.
Five parts, $5,600 total value
 Your Number
 Debt & Credit
 Pay Less Tax
 Earn More
 Invest Smart
 Protect Your Family
Legacy Wealth Blueprint Video Course (100+ lessons)
Usually $2,000
I picked 35 people from my email list. Each one gets a $4,100 scholarship, so you get my whole Wealth Plan bundle for $1,500. That's a $5,600 total value. I'm holding your spot until Monday, November 30, at 11:59 PM ET.
Don't want it? Reply to any of my emails and tell me you're passing. Then I can give your scholarship to someone else on my list.
My email list
$4,100 off for each winnerYou did what everyone told you to do: you got a good job, filed on time every April, and trusted your CPA or tax software.
Your CPA's job is to record last year accurately. HR's job is to run payroll.
Nobody's job was to sit down with your return before December 31 and tell you what to change next. So nobody did.
Filing taxes isn't the same as planning taxes.
A real comment from a tax forum, quoted word for word
“If it's all W-2... there is nothing you can do.”
Preston's answer
Handing HR an updated W-4 stops the interest-free loan to the IRS and puts your own cash back into your next paycheck.
Shield up to $24,500 of 2026 pay from federal income tax, as long as it comes out of your 2026 paychecks before Dec 31.
With a qualifying health plan, an HSA lets you pay medical bills you already have with tax-free dollars.
These three are the basics. Anyone on a W-2 can do them.
Some of you can go further, with moves most people never hear about: a second Roth inside your 401(k), or real estate and business moves if they fit your situation. Your plan checks which ones fit you and leaves out the ones that don't.
Your questionnaire tells us what you earn, what you owe, what you've saved, your benefits at work, and your goals. You can attach your tax return too. For most people, nobody ever looks at all of that together.
My team starts right there. We look for unused room, like the $21,600 of 457(b) room Renz never touched, or the HSA Heather left unopened for four years. Then we rank every move in order. For Mordechai, paying down a 24% card came ahead of every tax move.
Every move in your plan gets a dollar estimate and a deadline. Instead of guessing which video applies to you, you work down one clear list.
Your CPA files last year's return. Your Personal Wealth Plan shows what to change before this year ends, so you walk in with a ranked list they can check and help you execute.
$1,500, or 12 interest-free payments of $125 · Closes Mon, Nov 30 at 11:59 PM ET
The plan tells you what to do. The course and tools show you how. Your coach call answers your questions and gets you started, and the live Q&A on December 3 covers the last moves before December 31.
Fill out a short questionnaire about your income, debt, savings, and goals. You can attach your tax return too. Within 7 days, my team sends back a custom 20- to 25-page plan built around your numbers.
Built for Sam, an invented client: 41, single parent of two, $210,000 W-2 and a $45,000 side business. Seven moves, $80,850 in projected first-year value.
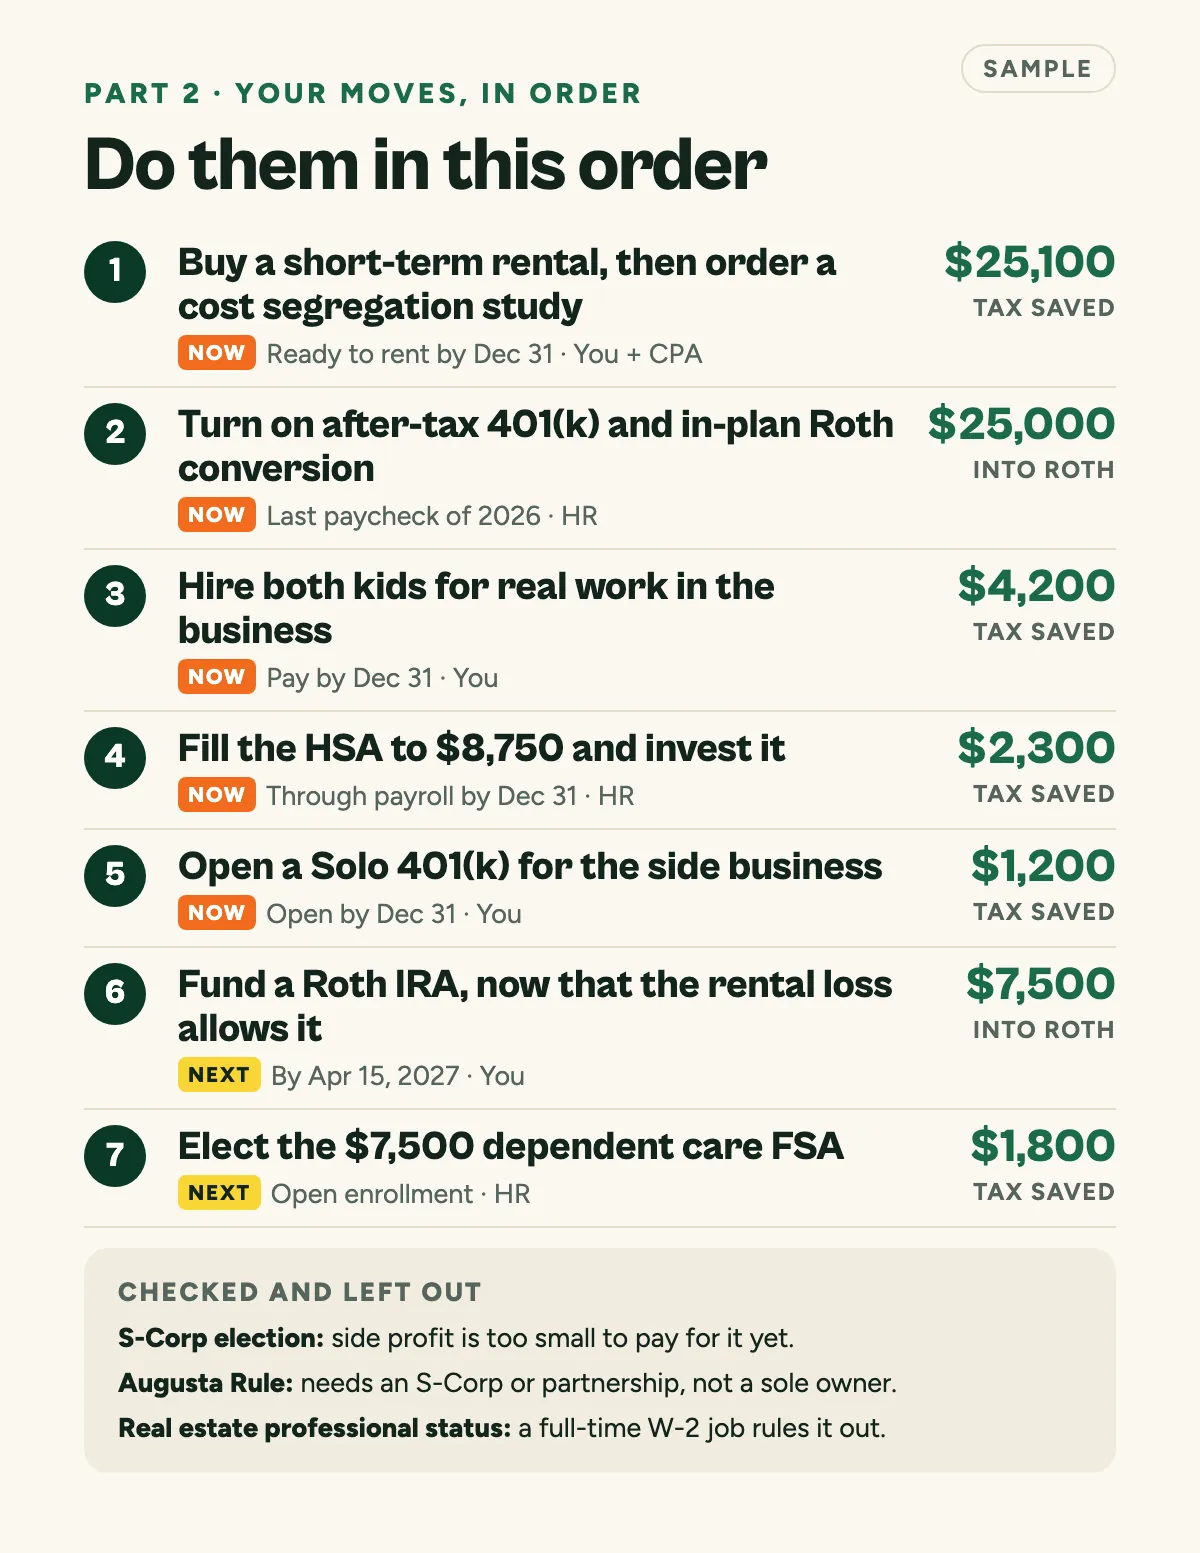
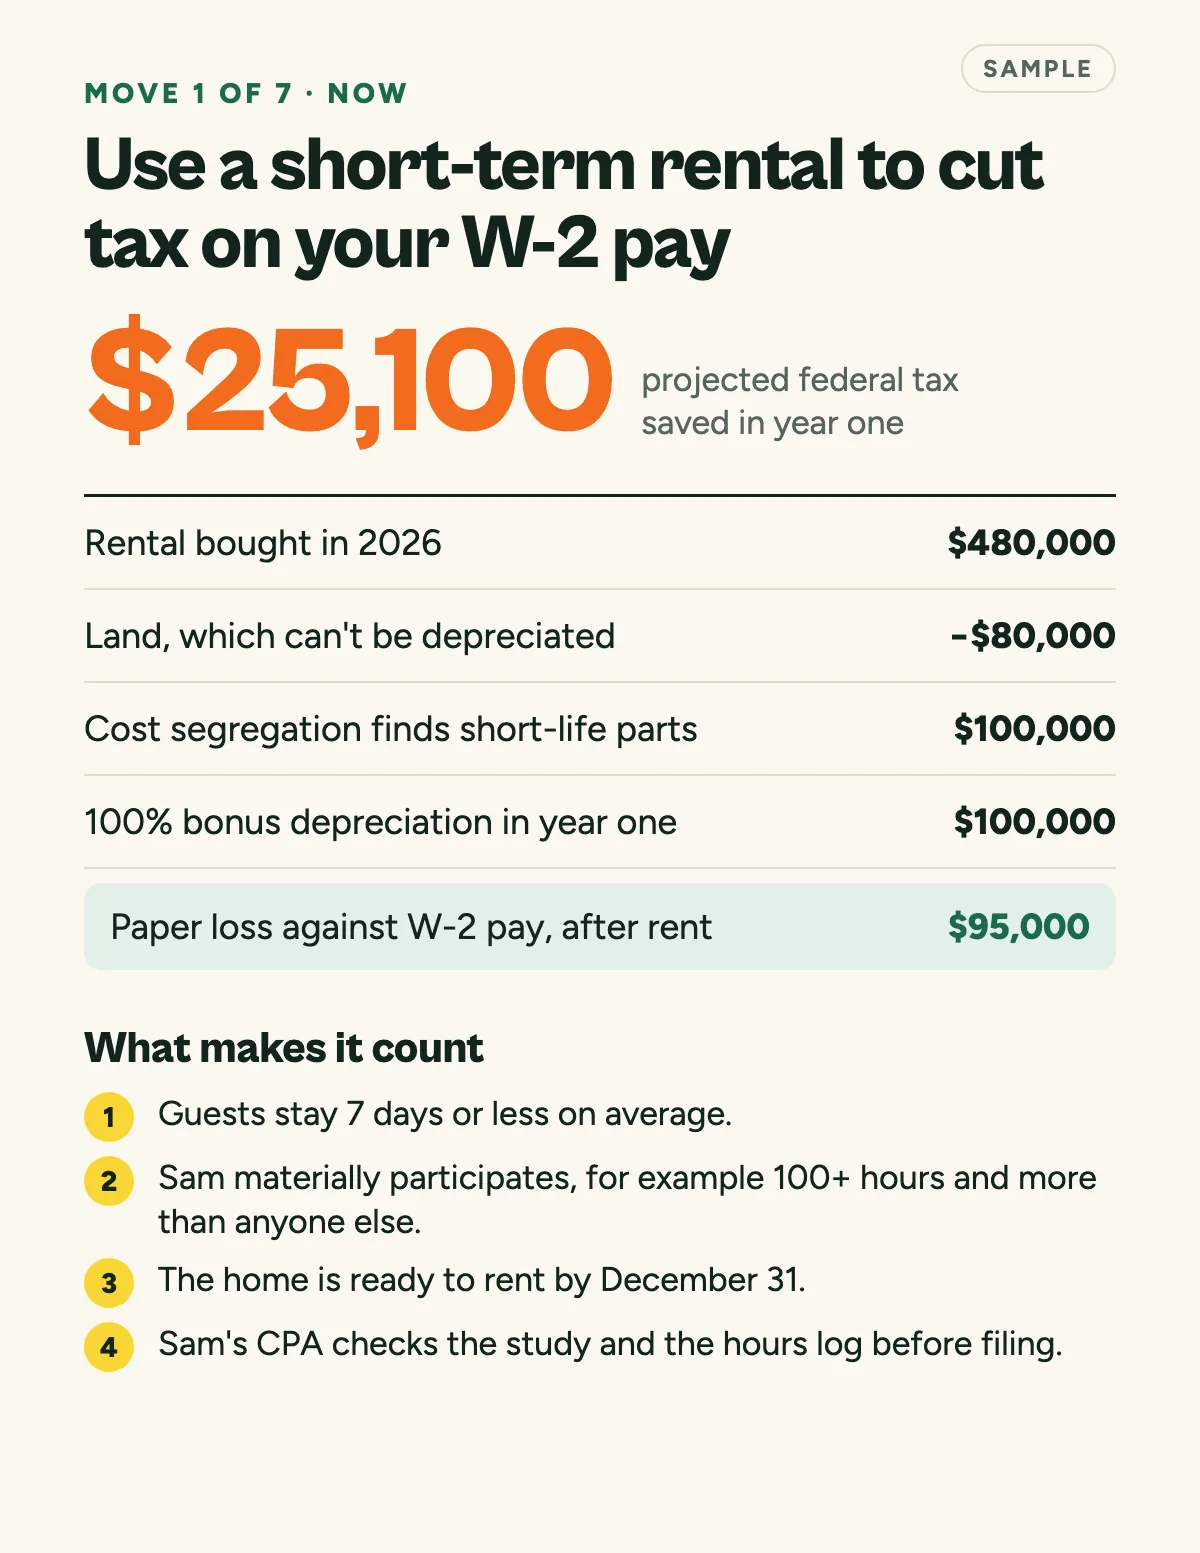
Most people never hear about these moves. They're legal and written into the tax code, but they rarely come up at tax time. Your plan shows which ones fit you, and which one to do first.
All 100+ video lessons from my $10K+ coaching program, unlocked the moment you join. Don't binge-watch it. Use it like a playbook: when your plan says "fix your W-4" or "open an HSA," pull up that exact video and follow along step by step.
Find the exact number that makes work optional, size your emergency fund, and direct every paycheck.
Pay off cards in the smartest order, raise your credit score, and learn how 0% business credit works if you own a business.
Dial in your W-4, HSA, 401(k), and Roth in order. Plus S-Corp elections, Solo 401(k), and the Augusta Rule for business owners.
Raise your income without quitting your job, from negotiating your next raise to building a side business.
How much to invest each month and where, starting with your 401(k) match through real estate and cost segregation.
Insurance, wills, and beneficiaries on a W-2, plus trusts and LLCs as your net worth grows.
After your plan arrives, you and a coach go through it together on a private call.
On Thursday, December 3, I'll go live to walk through the last-minute moves you can still make before December 31 so they count on your 2026 return. Then I'll stay on and answer your questions live. You'll get the link by email.
Put these 5 tools to work tonight while my team builds your custom plan. Each tool handles one step and sets up the next.
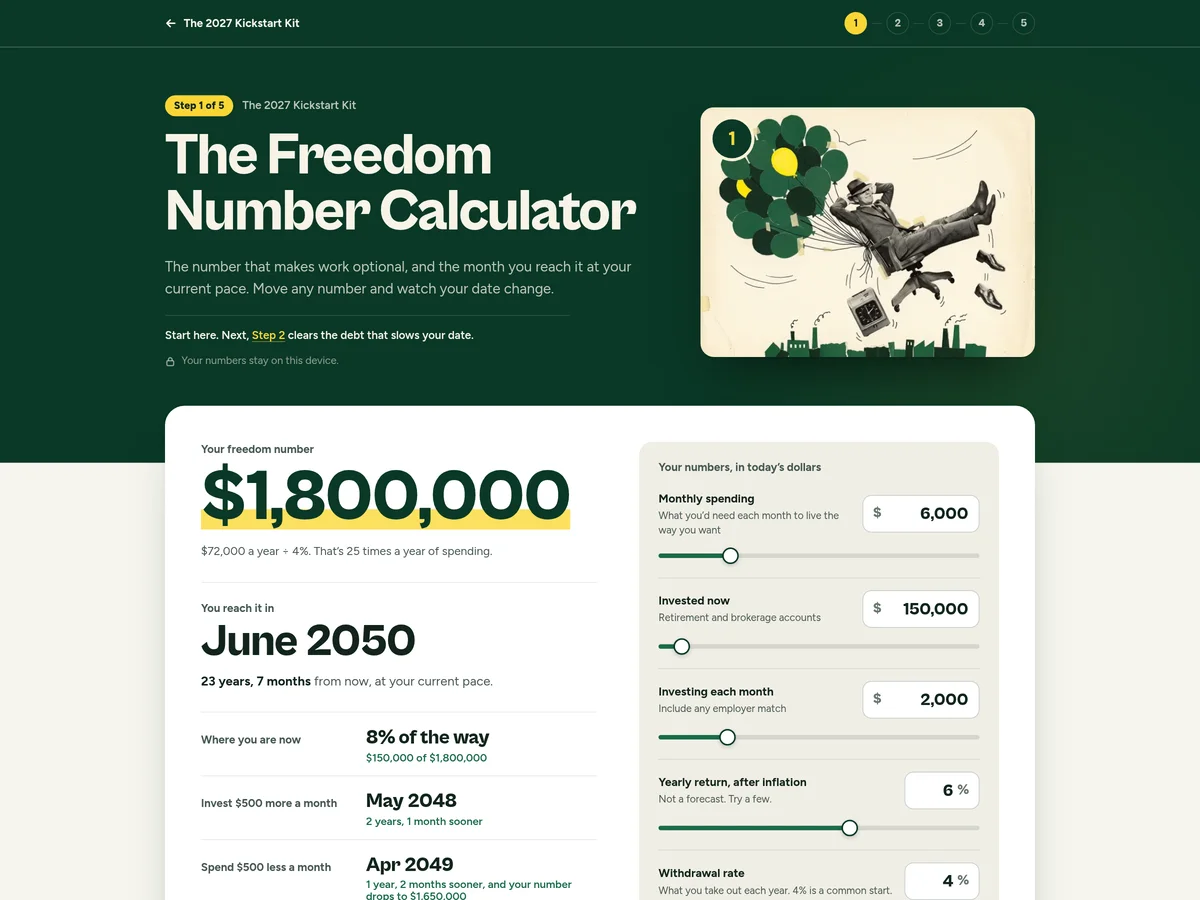 1
Plug in your numbers to see the exact amount that makes work optional, the month you'll hit it, and how many years you shave off by adding $500/mo.
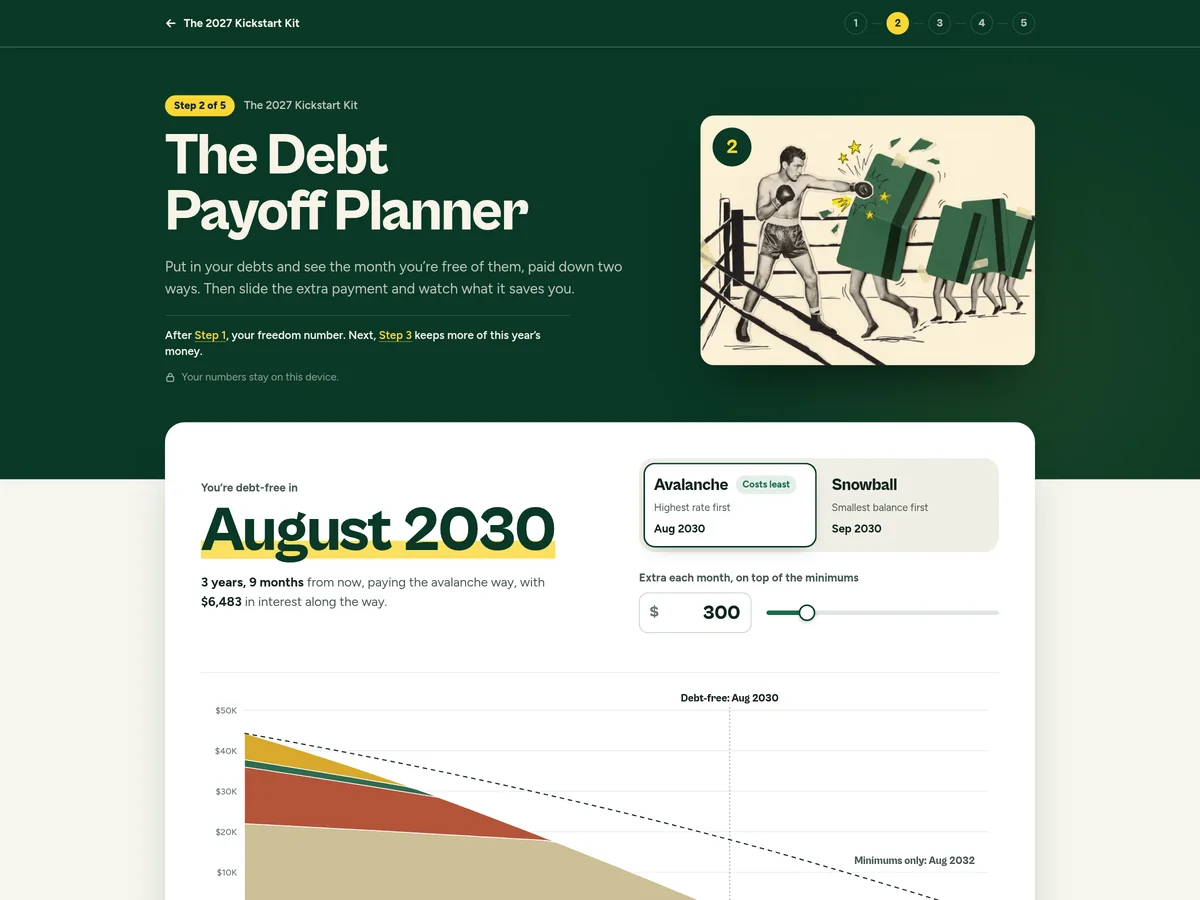 2
Enter your cards and loans to see your exact debt-free date, which balance to kill first, and how much interest one extra payment wipes out.
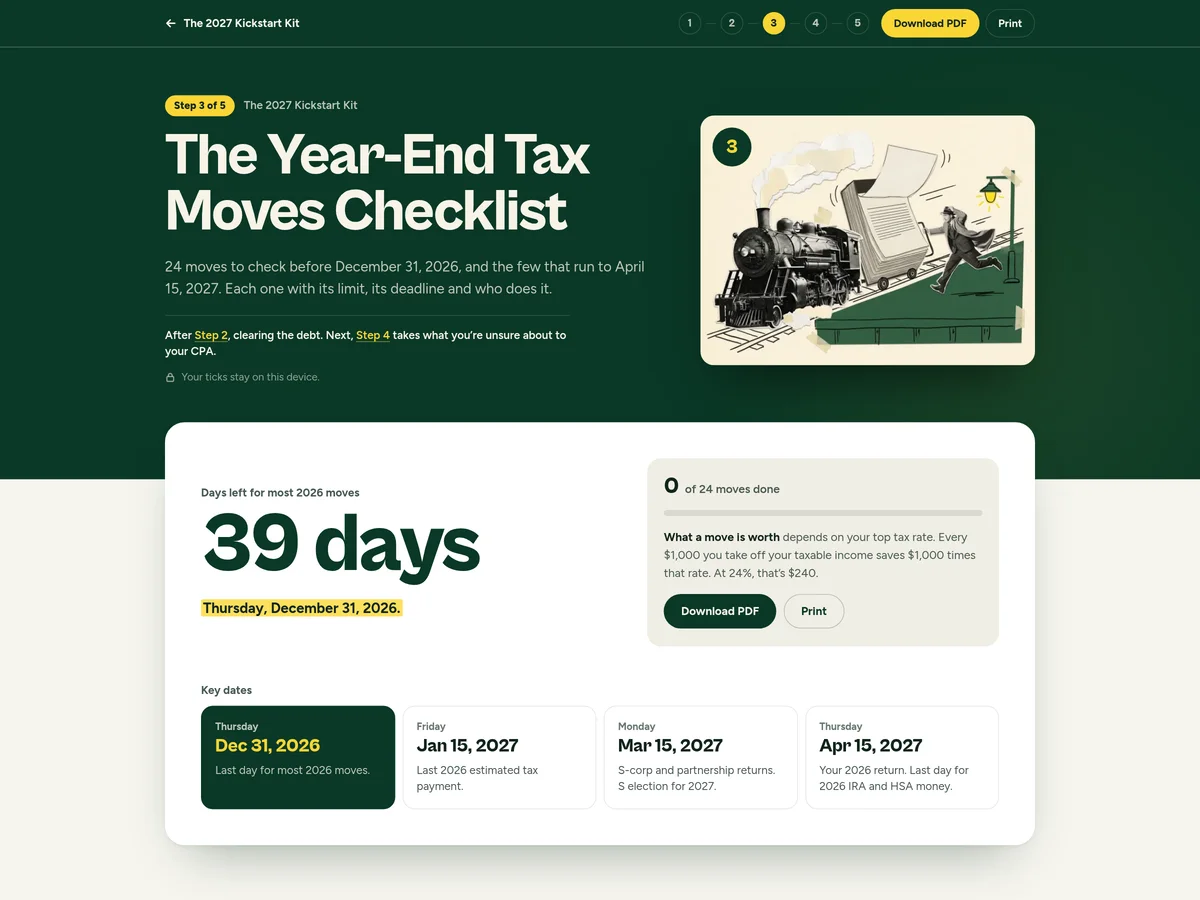 3
Every 2026 move that closes on December 31, with contribution limits, deadlines, and whether it's on you, HR, or your CPA.
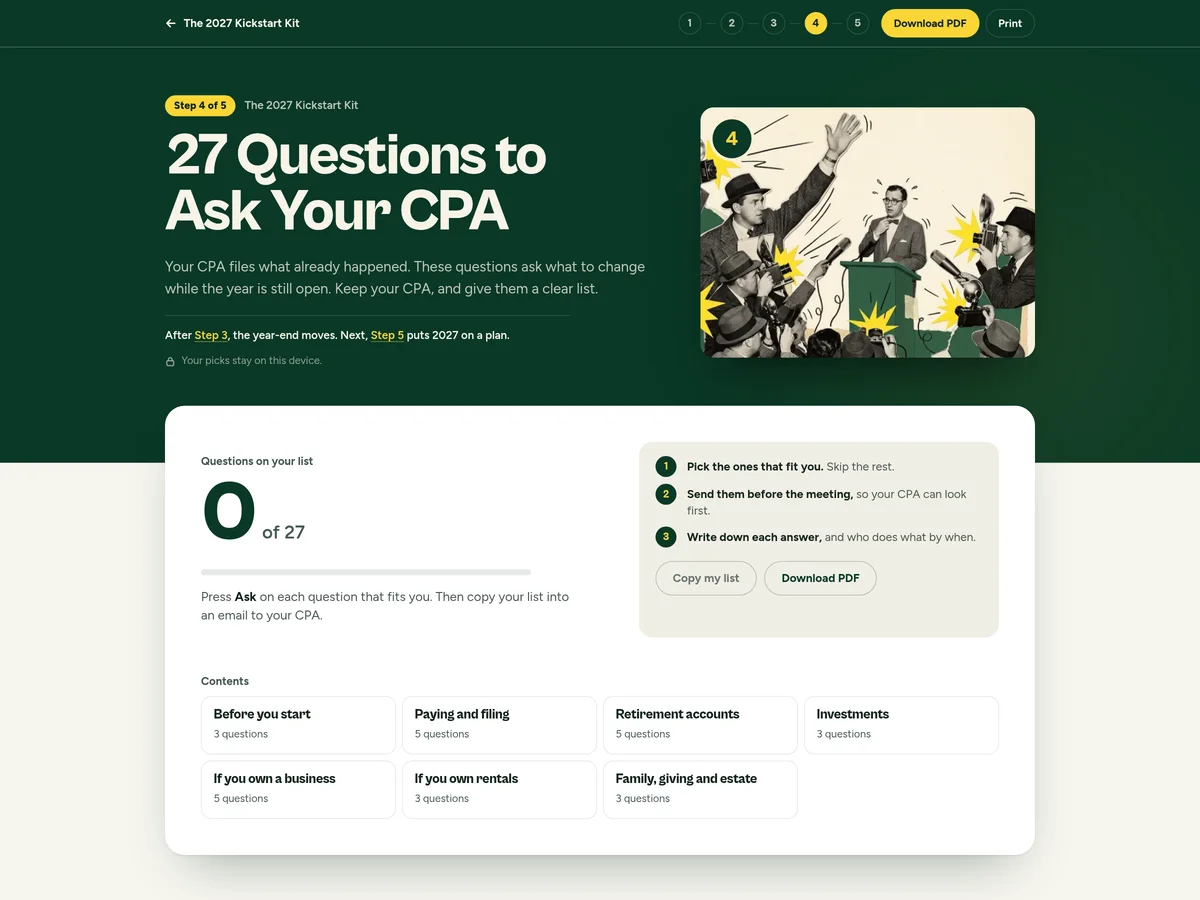 4
The exact questions most CPAs never bring up on their own, and why each one matters. Email the list before your next meeting.
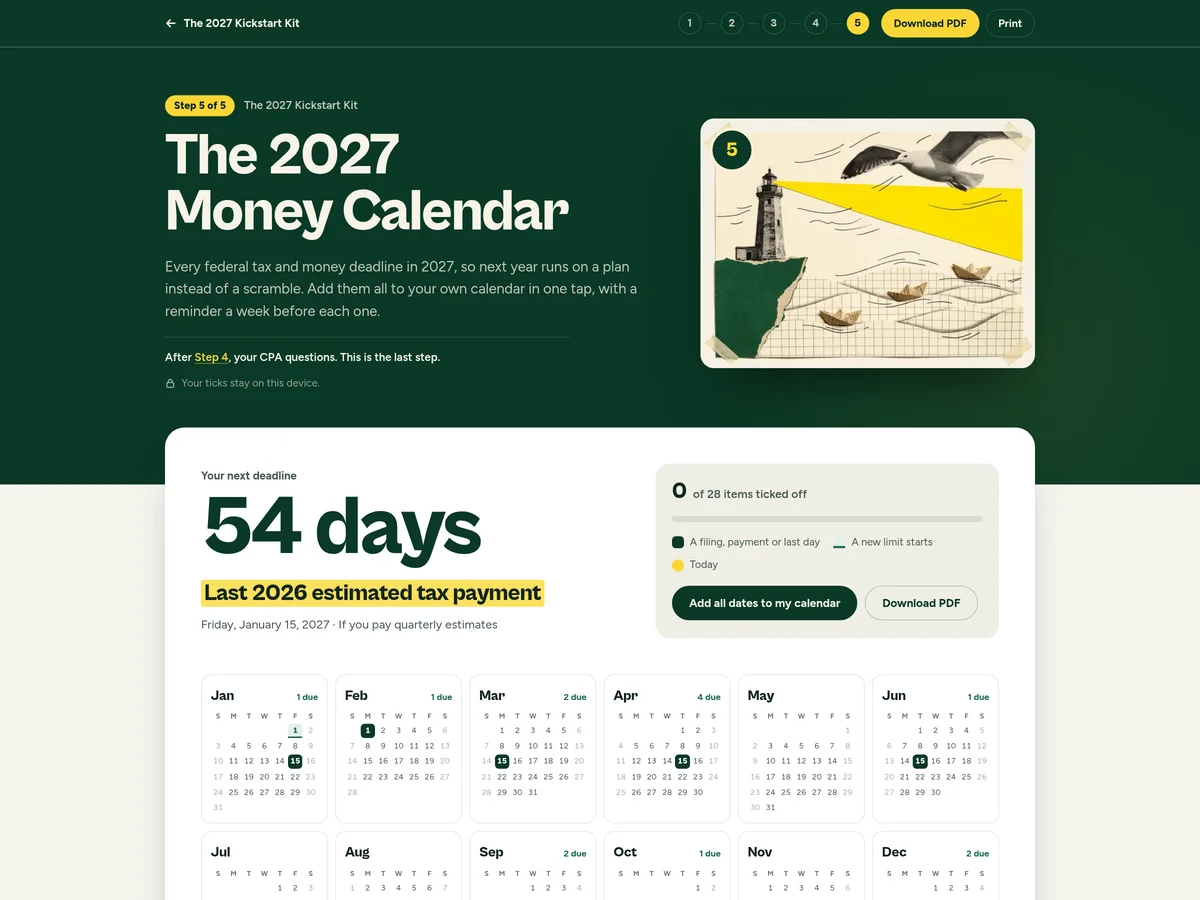 5
Every 2027 federal tax and money deadline added to your calendar in one tap, with automatic reminders one week early.
Or 12 interest-free payments of $125 · Covered by my $10,000 Value Promise
Real clients, first names only. Every number is projected for their first year.
Renz Public-sector W-2, age 39
Nobody told him it has its own $24,500 limit on top of his 403(b). One payroll form fixes it.
Mordechai ~$130,000 on cards
His plan paid down $30,000 of 24% cards before any tax move.
Zachary W-2, seven kids
His paychecks over-withheld all year. A new W-4 fixed it.
Heather S-Corp owner, age 45
She had an HSA-eligible plan for four years and never opened the HSA.
Jeanie $117,000 in student loans
A Solo 401(k) projects a lower tax bill and a lower loan payment.
“Just under a hundred thousand dollars.”
$1,500 or $125/mo · Covered by my $10,000 Value Promise
My team has built more than 500 plans. Across 300+ of those plans, the average projected first-year value is $85,871*. So $10,000 is the minimum floor I'm willing to put my name on.
You paid $1,500 for a custom plan showing at least $10,000 in projected first-year value, plus the video course, coach call, live Q&A, and 5 tools to carry it out.
Send one email to support@legacyinvestingshow.com within 30 days of receiving your plan. We refund 100% of what you paid, and you keep your 20- to 25-page plan.
Nothing in your financial life changes until you decide it does. You keep your job, your CPA, and your accounts. Let my team run your numbers first. If your plan comes in under $10,000, you send one email, get every dollar back, and keep the plan.
How first-year value is calculated: it adds up four projected numbers (tax you won't pay, cash flow freed up like card interest eliminated, money moved into your own accounts, and projected investment growth). We need your real numbers in the questionnaire to build it. All figures are projections, so actual savings depend on the moves you make.
Some 2026 tax moves close forever on December 31. Claim now, send your questionnaire right away, and you'll have your custom plan in 7 days with most of December left to act.
Unlock The Legacy Wealth Blueprint Video Course and The 2027 Kickstart Kit (open Step 3, The Year-End Tax Moves Checklist, first). Fill out your questionnaire. You can attach your tax return too.
My team reviews your numbers and sends your custom 20- to 25-page Personal Wealth Plan to your inbox.
Book your 30-minute 1-on-1 call with a coach and leave knowing your exact first move.
Make the moves marked "NOW" while they still count for 2026. Bring your questions to my live year-end Q&A on Thursday, December 3.
“One year I made about $500,000. My federal refund that year was $46.”
A $46 refund only meant my payroll withholding matched what I owed. It said nothing about whether I could have legally owed less. And nobody told me I even had a choice.
I've been where a lot of you are right now. When Bridget and I got married, we had $685 in the bank and lived in my parents' basement. Later, even when I was making good money on a W-2, I learned the hard way that earning money and keeping money are two different skills.
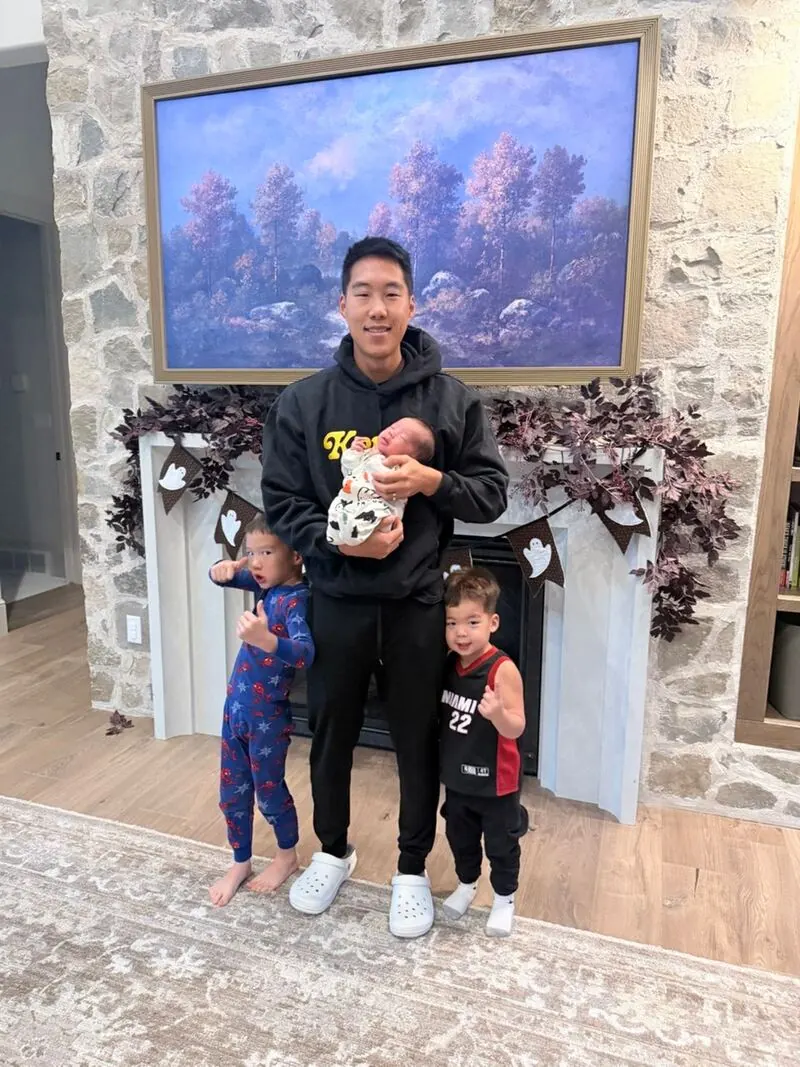
This Thanksgiving is my 35th birthday. Bridget and I reached financial freedom by 28, and a few weeks ago we welcomed our third son, Conrad. I own my time and get to be present with all four of them.
This birthday giveaway is my way of passing that forward. I picked 35 people for my 35th birthday, and you're one of them. With your $4,100 scholarship, you get my complete Wealth Plan bundle, a $5,600 total value, for $1,500, or 12 interest-free payments of $125.
Funny coincidence I noticed this week: from my 35th birthday on Thanksgiving to December 31 is exactly 35 days. Some of the biggest moves in your plan only count for 2026 if you make them before those 35 days run out.
If you don't want your scholarship, that's okay. Reply to any of my emails and tell me you're passing, so I can give it to someone else on my list.
Preston
P.S. Remember, you're covered by my $10,000 Value Promise. If your plan projects less than $10,000 in first-year value, one email gets you a full refund, and you keep the plan. Your $4,100 scholarship closes Monday, November 30, at 11:59 PM ET.
You're going to fix your taxes and debt sooner or later. Do it now while your 2026 paychecks still count, instead of letting another April slip by.
Scholarship closes in:
My $10,000 Value Promise: If your plan projects less than $10,000 in first-year value, one email gets you a full refund, and you keep the plan. Applies whether you pay in full or monthly.
After Monday, November 30 at 11:59 PM ET, your scholarship ends. On a $125,000 salary, 12 interest-free payments of $125/mo is about 1% of a month's pay.
If your plan projects less than $10,000 in first-year value, one email gets you a full refund, and you keep the plan. *Average across 300+ past plans. Results vary.
256-bit secure checkout · Instant access to your Video Course & 2027 Kickstart Kit
To celebrate turning 35 on Thanksgiving, I picked 35 winners from thousands of people on my email list for Prize #3. Each winner gets a $4,100 scholarship, so you get the $5,600 bundle for $1,500. Prize #1 (1 winner) gets my full $10K+ coaching program free, and Prize #2 (3 winners) get the Wealth Plan bundle free. Your spot is held until Monday at 11:59 PM ET. If you aren't interested, just reply "pass" to my email so I can give your spot to someone else.
Only the team building your plan sees your return. You upload it through a secure link inside your questionnaire (please never email it), and we never sell your data. A return from the year before works too, and if you don't have one handy, my team can build your plan from your questionnaire answers alone.
No hoops. If your plan projects less than $10,000 in first-year value, one email gets you a full refund, and you keep the plan. Just write to support@legacyinvestingshow.com within 30 days of receiving your plan, whether you paid in full or monthly through Splitit.
It adds up four projected items over your first 12 months: tax you won't pay, cash flow freed up (like credit card interest you stop paying), money you move into your own accounts (like a 401(k), HSA, or Roth), and projected growth on what you invest. Every move shows its own separate number so you can clearly see what is tax saved vs. your own money repositioned. All numbers are projections.
My team builds every plan (the same team behind 500+ past wealth plans, and I've personally reviewed 1,000+ returns). I am not a CPA or licensed advisor, and my team does not prepare or file taxes. Your plan identifies the forward-looking moves, and you check each move with your CPA before acting.
Yes, and keep your CPA. Their job is filing last year's return accurately. Your plan focuses on what to do next, and Step 4 of The 2027 Kickstart Kit gives you 27 exact questions to bring to them.
You and a coach walk through your finished plan, pick your exact first move, and map out what to bring to your CPA. If it fits your situation, your coach may also mention my full $10K+ coaching program. Joining is optional, and your plan is yours either way.
Yes. Your plan looks at your debt right alongside your taxes and investing, and puts every move in order (just like Mordechai's plan put paying off high-interest cards ahead of tax moves). And if your plan projects less than $10,000 in first-year value, one email gets you a full refund, and you keep the plan.
Yes. Your plan arrives within 7 days after you submit your questionnaire. Even if you claim on Monday night and submit right away, you'll have most of December left. Plus, you unlock Step 3 of The 2027 Kickstart Kit (The Year-End Tax Moves Checklist) the second you check out.
At checkout, Splitit splits the $1,500 into 12 monthly payments of $125 on a credit card you already have. You pay zero interest and zero fees. The $10,000 Value Promise covers you either way.
No catch. For my 35th birthday, I gave 35 winners a $4,100 scholarship off the bundle's $5,600 total value, so you pay $1,500 (or 12 interest-free payments of $125) until Monday night at 11:59 PM ET. There's no application and no sales call to start, and if your plan projects less than $10,000 in first-year value, one email gets you a full refund, and you keep the plan.